

Coforge Q3 Net Profit Declines 21.17% Sequentially; Industry Vendor Diversification Offers Growth Avenue
What Happened
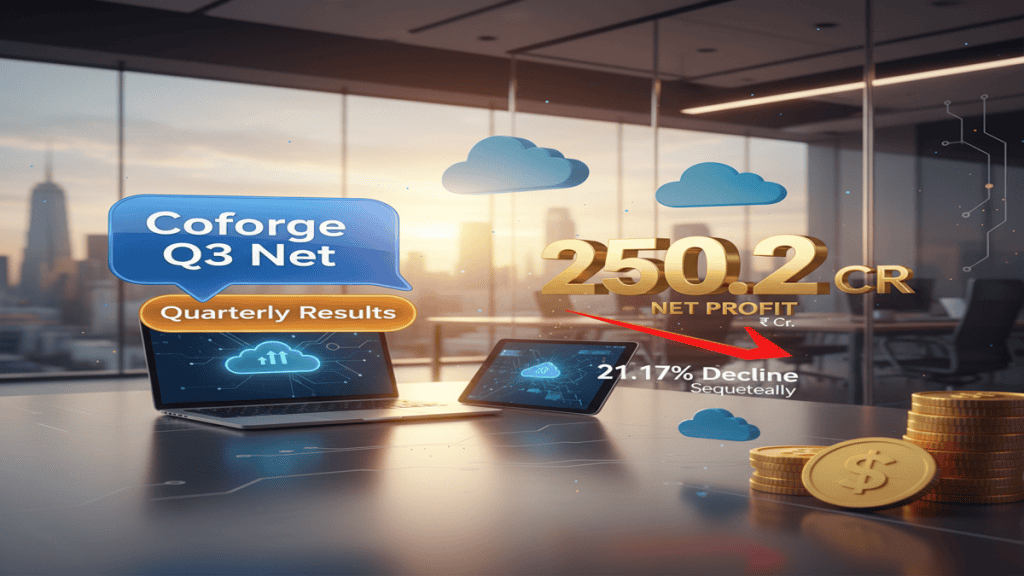
Coforge Limited has reported a sequential decline in profitability for the third quarter of fiscal year 2026. For the quarter ended December 2025, the company’s net profit stood at ₹250.2 crore, marking a 21.17% decrease from the ₹317.4 crore reported for the quarter ended June 2025. This drop in net income occurred despite a 13.54% sequential rise in revenue during the same period, with Q3 revenue reaching ₹4,188.1 crore.
The financial data was filed with the exchanges in compliance with SEBI’s Listing Obligations and Disclosure Requirements (LODR) regulations. The divergence between revenue growth and profitability has led to a closer examination of the company’s operational efficiency and cost structures.
In a concurrent industry development noted in March 2026, a structural shift is underway where large global enterprises are actively diversifying their vendor base for high-value, multi-year contracts. This trend is creating new opportunities for mid-cap IT service providers like Coforge to compete for deals previously dominated by Tier-1 firms.

This industry trend provides a long-term context to the company’s near-term performance, suggesting an expansion of its addressable market. It may allow the firm to bid for larger digital transformation projects, potentially altering its future growth trajectory.
Why This Matters
Scale of Development:
The quarterly performance is notable when set against the company’s financial scale. With a market capitalisation of ₹39,117.37 crore, the sequential profit decline highlights potential margin pressures. For the full financial year ended March 2025, Coforge reported an annual net profit of ₹812.1 crore on a total revenue of ₹12,050.7 crore. The profit drop between the June and December quarters represents a significant portion of its annual earnings base.
In contrast, the industry-wide development offers a potential long-term growth driver. The ability to compete for larger contracts directly addresses the company’s growth ambitions. A single large contract, for instance, worth ₹1,200 crore, would represent nearly 10% of the company’s annual revenue for the year ended March 2025.
Strategic Significance:
This development is strategically significant as it could reshape Coforge’s competitive positioning. Securing larger, multi-year contracts would enhance its revenue pipeline and reduce dependency on smaller projects. This shift could lead to improved operating leverage and better long-term margin profiles, though it may involve initial investment. The company’s balance sheet, with a debt-to-equity ratio of 0.17 as of March 2025, provides financial flexibility to pursue such opportunities.
This trend also validates the capabilities of mid-cap IT firms in executing complex projects, allowing Coforge to move up the value chain and challenge larger competitors more directly. Aligning its service offerings to capture these large deals will be critical for its future growth.
Financial Performance Context
Valuation Metrics (Current Market Data):
* Market Capitalisation: ₹39,117.37 crore
* P/E Ratio: 34.80
* Price-to-Book Ratio: 5.66
* EV/EBITDA: 18.34
Annual Operational Performance (For the Year Ended March 2025):
* Total Revenue: ₹12,050.7 crore with 26.2% YoY growth
* Net Profit: ₹812.1 crore
* Net Profit Margin: 6.74%
* Operating Margin: 10.61%
Balance Sheet Strength (As of March 2025):
* Total Debt: ₹1,070.4 crore
* Total Equity: ₹6,379.2 crore
* Debt-to-Equity Ratio: 0.17
* Current Ratio: 1.71
* Cash & Equivalents: ₹795.6 crore
Cash Flow Analysis (For the Year Ended March 2025):
* Operating Cash Flow: ₹1,237.1 crore
* Free Cash Flow: ₹622.7 crore
* Capital Expenditure: ₹614.4 crore
Quarterly Performance Trend:
* Q3 FY26 (ended December 2025): Revenue ₹4,188.1 crore, Net Income ₹250.2 crore
* Q1 FY26 (ended June 2025): Revenue ₹3,688.6 crore, Net Income ₹317.4 crore
* Growth (Q3 FY26 vs Q1 FY26): Revenue +13.54%, Net Income -21.17%
How Today’s News Impacts These Metrics:
The industry trend of vendor diversification supports the company’s long-term revenue growth trajectory, which stood at 26.2% for FY25. Securing larger deals could accelerate this growth. However, the Q3 profit decline highlights a potential risk to margins. The market will monitor if the pursuit of larger contracts leads to initial margin pressure, potentially impacting the annual Net Profit Margin, which was 6.74% for the period ending March 2025.
Market Sentiment & Impact Analysis
Overall Market Sentiment:
The overall market sentiment is reported as Positive with High strength, driven by long-term strategic opportunities that appear to outweigh short-term concerns from the recent quarterly results.
Key market drivers include:
- Increased Addressable Market: The structural shift of enterprises diversifying vendors is a primary catalyst, expanding the growth runway for mid-cap firms.
- Enhanced Earnings Visibility: The potential to win larger, multi-year deals could lead to more predictable revenue streams.
- Improved Competitive Positioning: This trend validates Coforge’s capabilities, enabling it to challenge larger Tier-1 competitors more effectively.
Stock-Specific Impact:
The expansion of the addressable market is viewed as a positive fundamental driver for the company. This development suggests a pathway to accelerate its revenue growth, which was 26.2% YoY for the year ended March 2025. Access to a new tier of large-scale enterprise contracts could improve long-term earnings visibility and strengthen the revenue pipeline.
Sector & Broader Market Implications:
This trend is viewed positively for the entire mid-cap IT services sector, signalling growing client confidence in their execution capabilities. This broadens the growth landscape beyond Tier-1 players and is a positive sentiment driver for the Nifty IT index.
Risk Factors to Monitor:
* Execution Risk: Securing larger deals brings the challenge of scaling delivery capabilities and project management for more complex contracts.
* Margin Pressure: Increased competition for large deals could lead to aggressive bidding, posing a potential risk to operating margins, which were 10.61% in FY25.
Share Price Movement (Current Market Data):
* Current Price: ₹1164.9
* 52-Week High/Low: ₹1994.0 / ₹1118.3
Company Shareholding & Float (Latest Available Data):
* Promoter Holdings: 0.83%
* Institutional Holdings: 65.95%
* The high institutional holding indicates significant ownership by professional fund managers.
Key Factors to Monitor
Immediate Catalysts (Next 1-3 months):
* Q4 FY26 Earnings: The upcoming quarterly results will be critical to assess if the Q3 profit decline was an anomaly.
* New Contract Disclosures: Announcements of large deal wins would serve as a major market-moving event.
* Management Commentary: The upcoming earnings call will be scrutinised for the outlook on margin trajectory and strategy for capturing large deals.
Medium-term Catalysts (Next 3-12 months):
* Revenue Recognition: The timeline for revenue recognition from any new large contracts will be key for financial years 2027 and beyond.
* Margin Evolution: The market will track whether the company can maintain or improve its operating margin of 10.61% (FY25) while pursuing larger contracts.
* Capital Expenditure: Announcements regarding capex for capacity expansion will indicate future growth investments.
Key Monitoring Metrics:
Key metrics for observation include:
* Execution progress on any newly announced large deals.
* Quarter-over-quarter revenue growth trends against the baseline of ₹4,188.1 crore reported in Q3 FY26.
* Margin evolution compared to the 10.61% operating margin reported for FY25.
* Cash flow generation, particularly free cash flow, which stood at ₹622.7 crore for FY25.
FAQs
1. What is the financial impact of this development?
The immediate financial impact is mixed, with a 21.17% sequential drop in Q3 FY26 net profit. However, the long-term development of vendor diversification could boost future revenue, which was ₹12,050.7 crore for the year ended March 2025.
2. How does this compare to the company’s existing business scale?
The quarterly revenue of ₹4,188.1 crore is a substantial part of its annual revenue of ₹12,050.7 crore (FY25). The ability to win deals that are a significant percentage of this annual figure highlights the transformative potential of the industry trend.
3. What are the execution risks or challenges?
The primary risk is execution on potentially larger and more complex contracts, which involves scaling up talent and project management. The company’s Current Ratio of 1.71 as of March 2025 provides a buffer to manage working capital needs.
4. How will this affect the company’s financial ratios?
The Q3 profit dip could pressure the Net Profit Margin, which was 6.74% for FY25. Conversely, winning large deals could improve revenue visibility and operating leverage, potentially boosting the Operating Margin (10.61% for FY25) in the long run.
5. What is the sector context and competitive positioning?
The key sector context is the trend of large enterprises diversifying IT vendors, creating opportunities for mid-cap players. This allows Coforge to compete more directly with Tier-1 firms. The company’s P/E ratio of 34.80 reflects market expectations of future growth.
6. What are the regulatory or compliance implications?
The company must continue to adhere to SEBI’s LODR regulations for timely disclosure of financial results and any material events, such as the signing of large contracts.
7. What are the key metrics to monitor going forward?
Key metrics to monitor include:
* Revenue Growth: Performance against the Q3 FY26 revenue of ₹4,188.1 crore.
* Margin Trends: Any deviation from the annual operating margin of 10.61% (FY25).
* Debt Levels: Changes in total debt from the ₹1,070.4 crore reported as of March 2025.
* Execution Milestones: Progress updates on any new large contracts.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.